
Advances exceed Rs 300 Bn YTD growth while deposits increased by over Rs 250 Bn
Net Interest Income rises 24% YoY, reflecting strong performance
Asset quality strengthens, with Net Stage 3 ratio at 1.09%
Liquidity and Capital Strength continue to support Growth
Amid shifting economic dynamics, Hatton National Bank PLC (HNB) recorded a solid financial performance for the nine months ended September 2026. Group Profit After Tax (PAT) reached Rs 33.6 Bn, while the Bank recorded a PAT of Rs 33.0 Bn.
Balance sheet expansion during 9M 2026 was a key contributor to the Bank’s performance, with Gross Advances recording a Year-to-Date (YTD) increase of Rs 313.5 Bn, equivalent to 20.7% growth. This was complemented by Deposit growth of Rs 251.7 Bn, a 12.8% YTD. Amid a higher interest rate environment, the Bank preserved a healthy CASA ratio of 32.0%, supporting a well-balanced funding mix.
The Bank recorded a 23.6% YoY increase in Net Interest Income (NII) to Rs 85.5 Bn, while Net Interest margin (NIM) stood at 4.50%. Strong lending momentum drove a 19.7% increase in interest income, which translated into stronger NII growth as interest expenses rose at a comparatively lower rate of 16.6% despite policy-driven rate pressures.
A notable improvement in fee-based income further strengthened the Bank’s revenue profile, with Net Fee and Commission income recording a 25.4% YoY increase to Rs 20.6 Bn. Increased card and digital transactions, higher trade finance activity and growth in leasing and other services contributed to the improved performance. Exchange-related income also recorded a notable improvement during the period, reflecting gains from foreign currency position and revaluation movements.
Strong growth across the Bank’s income streams translated into a 22.9% YoY increase in Total Operating Income to Rs 112.7 Bn. Total Operating Expenses increased by 13.6%, primarily on account of higher other operating expenses, partly attributable to investments in strategic transformation initiatives. The cost-to-income ratio stood at a well-managed 36.1%.
Strong revenue growth and continued cost discipline drove a 28.8% YoY increase in Pre-impairment Operating Profit to Rs 71.9 Bn, highlighting the quality of the Bank's earnings performance.
Growth in lending portfolio was accompanied by impairment provisioning of Rs 5.3 Bn, during the period, compared to an impairment reversal of Rs 7.5 Bn in the corresponding period of the previous year. The Bank maintained a Net Stage 3 ratio of 1.09% and a Stage 3 Coverage ratio of 73.46%, highlighting the continued focus on managing credit risk and maintaining the quality of its loan portfolio.
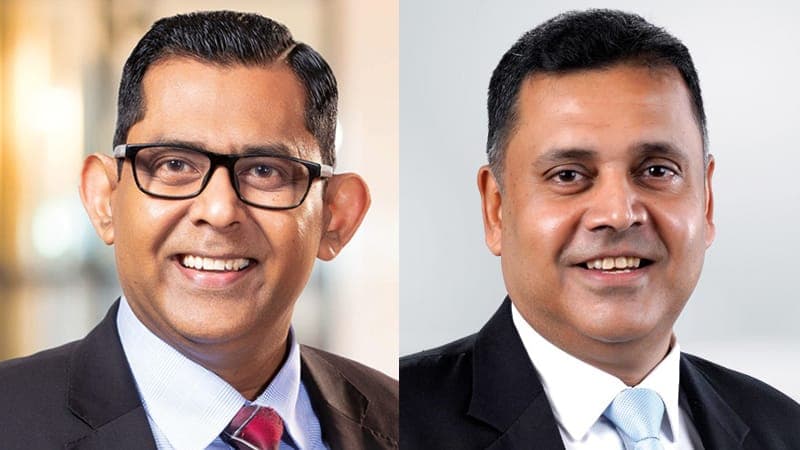
Commenting on the performance, Mr. Damith Pallewatte, Managing Director / Chief Executive Officer of HNB PLC, stated, “As the domestic economy continued to adjust to evolving economic conditions, HNB delivered a strong financial performance for the nine months ended September 2026. We continued to see healthy growth in both lending and deposits, while maintaining a balanced funding mix and a sound CASA position. As we expanded our business, we remained measured in our approach to impairment provisioning, while maintaining strong capital and liquidity positions. Our focus has been on growing responsibly, managing risks effectively and ensuring that the Bank remains well positioned to support its customers.
At the same time, we continue to invest in building the HNB of the future. Through our OneHNB approach, we are working towards bringing our capabilities together to offer customers more seamless solutions under one roof. We are strengthening our digital offering while continuing to improve our infrastructure, operations and governance.
I am grateful to our customers for their continued trust, our employees for their dedication, and our investors and stakeholders for their confidence in HNB. As we look ahead, we will continue to build on our strengths, accelerate our transformation and invest in the capabilities needed to meet the changing expectations of our customers. Our ambition is to make HNB a stronger, more agile and future-ready institution, delivering sustainable growth and long-term value for all our stakeholders.”
The Bank’s balance sheet continued to expand, with total assets reaching Rs 2.69 Tn as at September 2026, representing a YTD growth of 12.7%. Gross loans and advances stood at Rs 1.82 Tn, while the Deposit base reached Rs 2.21 Tn. HNB also maintained sound capital and liquidity positions, with a Tier I Capital Adequacy Ratio of 14.26%, a Total Capital Adequacy Ratio of 16.59% and an All Currency Liquidity Coverage Ratio of 165.32%. This provides the Bank with sufficient headroom to support future business growth while remaining comfortably within regulatory requirements.
Rated AA-(lka) by Fitch Ratings Lanka Limited, HNB continued to receive recognition for its performance across key business segments. During the period, the Bank was named “Best Bank for Large Corporates in Sri Lanka 2026” by Euromoney, “Best Bank in Sri Lanka” by The Banker and “Sri Lanka’s Strongest Bank” by The Asian Banker. HNB also received The Asian Banker’s “Best Retail Bank in Sri Lanka” award for the 16th time, alongside recognition as “Best Retail Bank” and “Best SME Bank” by Global Business Magazine for 2026. The Bank was also named “Sri Lanka’s Best Corporate Citizen 2025” by the Ceylon Chamber of Commerce.