

September, 22, 2026
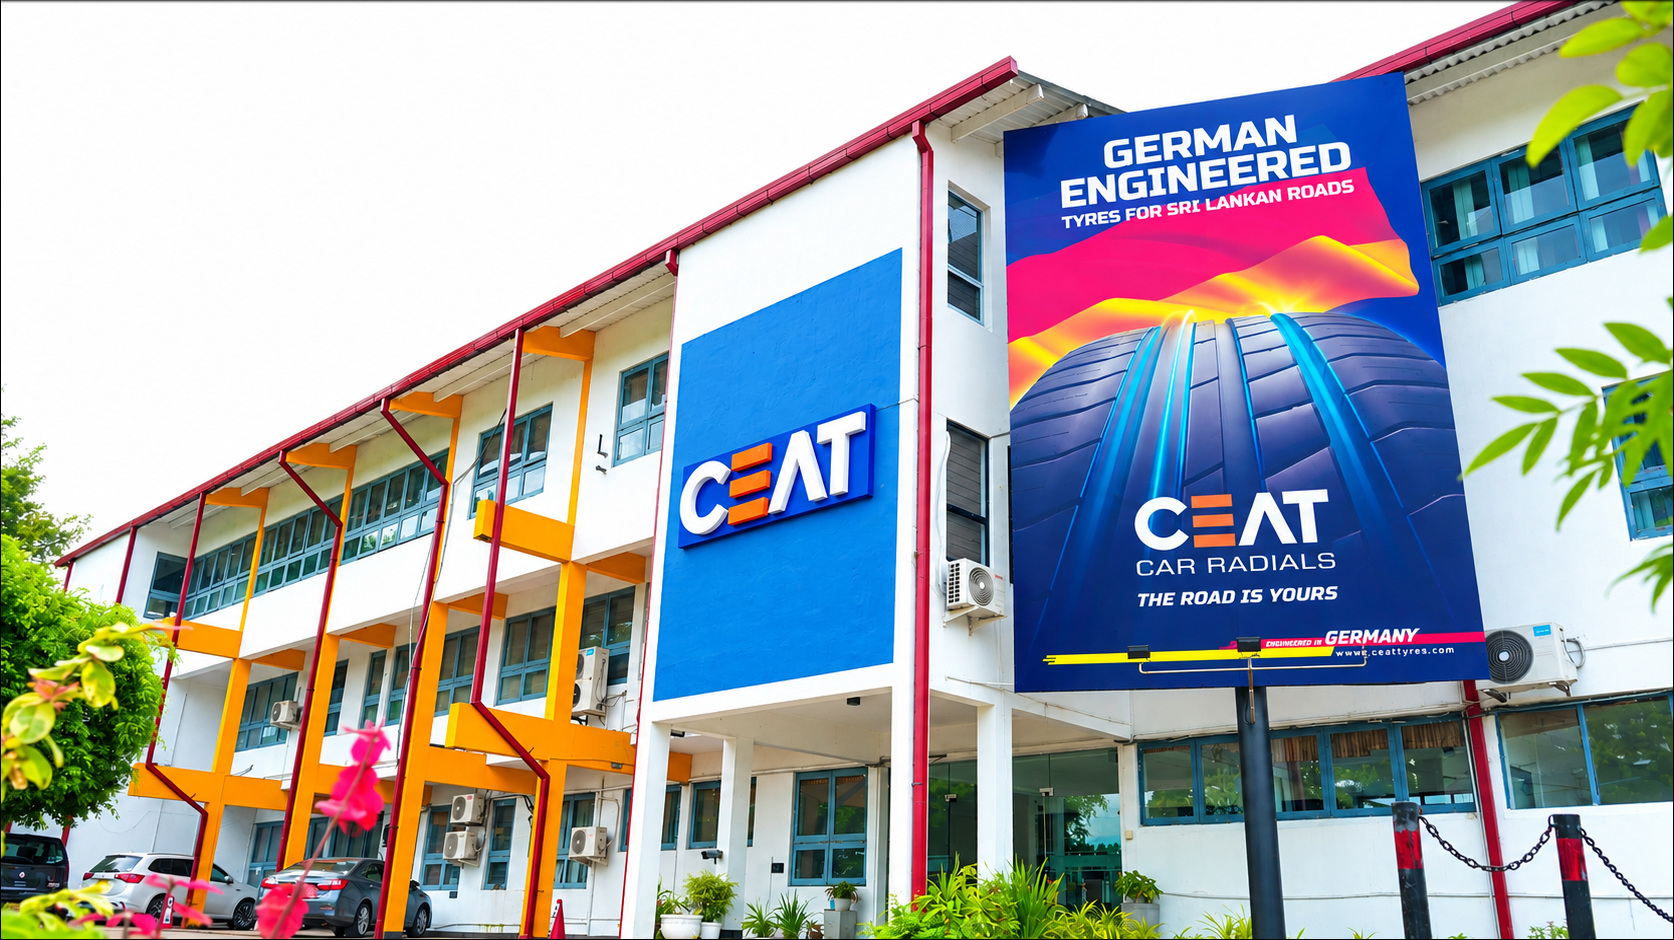
Sri Lanka’s leading tyre manufacturer CEAT Kelani Holdings (CKH) has retained its National Long-Term Rating of ‘AA+(lka)’ with a ‘Stable Outlook’ from Fitch Ratings for the sixth consecutive year, reinforcing the company’s sustained financial resilience and established leadership in Sri Lanka’s pneumatic tyre manufacturing sector.
The ‘AA+(lka)’ rating is the second-highest national rating on Fitch’s scale and reflects a very strong capacity to meet financial commitments. In affirming the rating, Fitch said CKH’s established leadership in the domestic pneumatic tyre manufacturing sector and resilient financial profile were key strengths, while noting the company’s exposure to price-sensitive, cyclical and highly competitive end-markets.
The Stable Outlook reflects Fitch’s expectation that CKH will maintain its market position amid rising input costs and intensifying competition from imported tyres. It also reflects Fitch’s expectation that the company will preserve adequate credit metrics despite periods of weaker earnings and elevated investment requirements.
Commenting on the latest rating, CEAT Kelani Holdings Chairman Mr Chanaka De Silva said: “A credit rating is ultimately a measure of confidence in an organisation’s ability to make sound decisions today while remaining financially equipped to pursue its ambitions for tomorrow. For CEAT Kelani, maintaining this rating through successive cycles reinforces the importance we place on disciplined stewardship, operational adaptability and investment in the long-term strength of the business. We remain focused on building a stronger, more competitive and increasingly capable manufacturing enterprise that can create sustainable value for all our stakeholders.”
The rating agency said it expects CKH to maintain its leading position in Sri Lanka’s pneumatic tyre manufacturing industry, supported by its established brand and extensive dealer network. It also noted that CKH’s adaptive pricing strategies should help mitigate market volatility and preserve market share across key segments, while planned production facility upgrades are expected to enhance product quality, particularly in the radial tyre segment, and strengthen the company’s competitive positioning.
Fitch expects CKH to face near-term margin pressure from rising prices of imported and locally sourced raw materials and higher conversion costs arising from increased energy prices. Fitch said CKH’s robust financial profile, characterised by low leverage and sound liquidity, should provide a cushion against a challenging operating environment.
CKH’s liquidity position provides further support to its financial profile. The rating agency expects maintenance capital expenditure of Rs. 700 million annually over the next four years, together with growth capital expenditure of Rs. 2.5 billion in FY27 and Rs. 1.5 billion in FY28. CKH is the tyre market leader in Sri Lanka, and the new investment will reinforce its role as a key contributor to the national economy and a trusted partner to the transport sector.
The CEAT brand originated in Italy and is backed by extensive research and testing facilities in India and Germany. CEAT was ranked Sri Lanka’s most valuable tyre brand by Brand Finance and named the ‘Most Loved Tyre Brand’ in Sri Lanka in 2025 and 2026 by LMD.
Video Story